admin
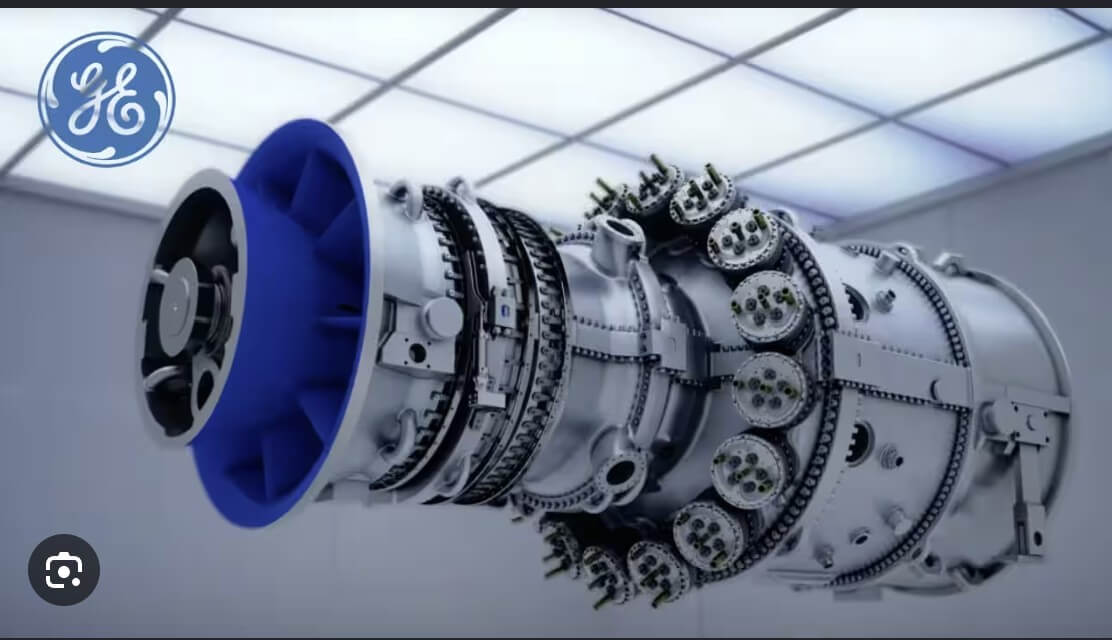
India’s power sector narrative is universally told through high-profile headlines: massive renewable generation targets, high-voltage transmission corridors, battery energy storage systems (BESS), and power-hungry artificial intelligence data centers.
Yet beneath the market excitement lies an indispensable operational layer that receives far less attention: the specialized engineering, modernization equipment, and aftermarket services required to keep India’s massive existing and upcoming baseload power fleet running at peak availability.
This structural dynamic marks the foundation of the GE Power India turnaround. Listed on Indian bourses as GE Power India Limited (NSE: GVPIL | BSE: 532309), the company is executing one of the most radical corporate transitions in the domestic capital goods landscape:
The core investment thesis is not merely that “thermal power is back.” Rather, it is that India’s structural surge in electricity intensity requires its thermal and hydro assets to run harder, longer, and with far higher efficiency than ever before.
Investors evaluating cyclical recoveries, balance sheet cleanups, and multibagger stocks will find the operational mechanics of this restructuring particularly compelling.
1. Executive Summary: The Structural Shift at a Glance
For over a decade, GE Power India (GEPIL) was burdened by legacy turnkey Engineering, Procurement, and Construction (EPC) projects. These multi-year contracts subjected the company’s balance sheet to fixed-price raw material spikes, delayed milestone payments from state electricity boards, and severe liquidated damages.
Today, management has completely re-engineered that business model. The company has designated Core Services as its primary growth and profitability engine.
                          GE POWER INDIA: STRATEGIC SHIFT

       LEGACY BUSINESS MODEL                          RESTRUCTURED BUSINESS MODEL
 ┌───────────────────────────────┐              ┌─────────────────────────────────────┐
 │ • Lump-sum EPC Contracts      │              │ • High-Margin Core Services         │
 │ • High Working Capital Lockup │  ────────►   │ • 30-to-90 Day Outage Execution     │
 │ • Volatile Operating Margins  │              │ • Proprietary OEM & Non-OEM Spares  │
 │ • Severe Execution Liabilities│              │ • Cash-Accretive Technology Supply  │
 └───────────────────────────────┘              └─────────────────────────────────────┘
The operational achievements of this pivot are evident across three critical dimensions:
- Margin Expansion: Shifting from deep operational losses to a sustainable double-digit operating margin profile targeting an 11% EBITDA floor.
- Balance Sheet De-Risking: Resolving contentious legacy litigations, highlighted by milestone recoveries from Bharat Heavy Electricals Ltd (BHEL) and private developers.
- Portfolio Simplification: Divesting heavy fabrication operations—including the demerger of the Durgapur boiler manufacturing facility to JSW Energy—to establish an asset-light engineering footprint.
2. Macro Backdrop: Physical Realities of India’s Power Grid
To understand why the GE Power India turnaround is backed by strong tailwinds, one must analyze the physical constraints of India’s electrical grid.
According to data compiled by the Central Electricity Authority (CEA), India’s peak electrical demand has crossed 250 gigawatts (GW). Rapid industrial expansion under Make-in-India programs, extensive urban electrification, and recurring heatwaves continue to drive power consumption higher.
            INDIA'S POWER REALITY: CAPACITY VS. ACTUAL GENERATION

       Total Installed Capacity (~440+ GW)         Actual Electrical Units Generated (TWh)
       ┌───────────────────────────────┐           ┌───────────────────────────────┐
       │   Thermal (Coal/Lignite) ~48% │           │   Thermal Generation ~73%     │
       ├───────────────────────────────┤           ├───────────────────────────────┤
       │   Renewables (Solar/Wind) ~33%│           │   Renewables Generation ~18%  │
       ├───────────────────────────────┤           ├───────────────────────────────┤
       │   Hydro & Nuclear ~19%        │           │   Hydro & Nuclear ~9%         │
       └───────────────────────────────┘           └───────────────────────────────┘
       *Source: Central Electricity Authority (CEA) Disclosures
While renewable capacity additions are expanding rapidly, green power generation remains intermittent. Solar farms generate electricity for 5 to 7 hours daily at capacity factors between 20% and 24%, while wind energy fluctuates seasonally. Consequently:
- Coal-fired thermal power supplies over 70% of actual units consumed nationwide.
- Average thermal Plant Load Factors (PLFs) across utilities have climbed from ~55% in FY21 to 68%–74%+, with supercritical base plants running at >85% capacity.
- Running thermal plants continuously under heavy load accelerates thermal stress on boiler tubes, turbine rotors, and high-pressure steam pipes.
- The Ministry of Power has extended retirement timelines for older coal units, issuing formal directives for Renovation & Modernization (R&M) and Life Extension (LE) programs to maintain baseload stability.
This structural tailwind is central to the GE Power India turnaround thesis: every gigawatt of power capacity running harder requires ongoing maintenance, parts, and specialized engineering support.
For broader sector setups, review our dedicated screening on breakout stocks.
3. Core Business: The Engine of the GE Power India Turnaround
Tracing its operational roots through Alstom’s power equipment business in India, GEPIL maintains intellectual property rights and service access to an extensive installed power fleet.
A key driver in the GE Power India turnaround is the rapid scaling of high-margin aftermarket support. The company operates across three complementary divisions:
                                GE POWER INDIA ECOSYSTEM

       CORE PRODUCTS                      SERVICES & RETROFITS               DIGITAL & EMISSIONS
 ┌─────────────────────────┐           ┌────────────────────────┐         ┌─────────────────────────┐
 │ • Supercritical Boilers │           │ • Plant Life Extension │         │ • Flue Gas Desulfurization│
 │ • Steam Turbines        │  ───────► │ • Rotor/Blade Upgrades │ ──────► │ • De-NOx Solutions      │
 │ • Turbogenerators       │           │ • Planned Outages (O&M)│         │ • Plant Automation & DCS│
 │ • Hydro Turbines        │           │ • Non-OEM Fleet Spares │         │ • Efficiency Monitoring │
 └─────────────────────────┘           └────────────────────────┘         └─────────────────────────┘
A. Core Services and Plant Life Extension
This division forms the foundation of current operations. Key revenue streams include:
- Planned Outage Maintenance: Managing complete turbine and boiler overhauls during statutory plant shutdowns.
- Component Modernization: Supplying high-pressure turbine rotors, upgraded blading, and advanced boiler coils to improve heat rates and reduce auxiliary fuel consumption.
- Life Extension Solutions: Delivering comprehensive engineering packages that extend operational lifespans by 15 to 20 years at a fraction of greenfield replacement costs.
- Non-OEM (oOEM) Servicing: Actively capturing service mandates on equipment built by third-party manufacturers, including BHEL, Siemens, and Chinese OEMs.
B. Steam Power and Industrial Turbines
Supplying supercritical boiler modules, steam turbines, turbogenerators, and heat recovery steam generators (HRSGs) for heavy industrial users and utility operators.
C. Air Quality Control Systems (AQCS)
Providing environmental compliance technologies, including Flue Gas Desulfurization (FGD) systems and electrostatic precipitators (ESPs) designed to limit industrial emissions.
4. Business Model Shift: Turnkey EPC vs. Core Services
The financial metrics of the GE Power India turnaround reflect a fundamental divergence in unit economics between contracting work and specialized engineering services:
| Operational Dimension | Legacy Lump-Sum Turnkey EPC | Restructured Core Services |
| Project Timeframe | 36 to 60 Months (Extended risk exposure) | 30 to 90 Days (Rapid outage cycle) |
| Gross Margin Profile | 12% to 18% (Vulnerable to raw material swings) | 35% to 50%+ (Proprietary IP pricing) |
| EBITDA Margin Target | Negative to 3% | 11% to 15%+ (Management baseline) |
| Working Capital Days | 120 to 200+ Days (Severe milestone retention) | 30 to 60 Days (Fast milestone collections) |
| Balance Sheet Exposure | High (Heavy performance guarantees) | Low (Asset-light engineering) |
| Customer Dynamic | Transactional, dispute-prone contracting | Long-term operational partnership |
                       REVENUE CONVERSION CYCLE COMPARISON

  EPC Cycle:
  [Year 1: Civil Works] ──► [Year 2: Equipment Supply] ──► [Year 3: BOP] ──► [Year 4-5: Retention Disputes]
  *High capital lockup, high vulnerability to inflation, delayed cash realization.

  Services Cycle:
  [Day 1: Outage Planning] ──► [Day 30: Rotor/Boiler Overhaul] ──► [Day 60: Performance Tests] ──► [Day 90: Cash Settlement]
  *Fast turnaround, immediate revenue realization, rapid cash conversion.
This structural dynamic explains why the GE Power India turnaround differs fundamentally from traditional EPC contractors:
- Critical Outage Economics: Power utilities cannot postpone planned overhauls indefinitely without risking catastrophic trips. When peak power demand is high, an offline 660 MW unit costs power operators millions of rupees each day in lost output.
- Proprietary Moats: Supercritical turbines operate under steam temperatures exceeding 560°C and pressures above 240 bar. Plant operators rely exclusively on verified OEM engineering and specialized tooling to protect these capital assets.
- Penetration of Non-OEM Fleets: GEPIL has successfully expanded into servicing non-OEM equipment. In recent quarters, over 50% of new service bookings have originated from third-party equipment fleets, multiplying the company’s addressable market.
Discover more detailed balance sheet evaluations through our fundamental analysis library.
5. Financial Forensics: Tracking the GE Power India Turnaround
A thorough review of the GE Power India turnaround financials reveals how revenue contraction was deliberate, paving the way for operational recovery:
Multi-Year Performance Overview
| Financial Metric (₹ Cr) | FY 2021-22 | FY 2022-23 | FY 2023-24 | FY 2024-25 | FY 2025-26 |
| Revenue from Operations | ₹2,620 | ₹1,796 | ₹1,039 | ₹1,047 | ₹1,269 |
| YoY Revenue Growth (%) | -21.6% | -31.4% | -42.1% | +0.8% | +21.2% |
| Operating EBITDA | -₹204 | -₹335 | -₹160 | -₹4 | ₹155 |
| EBITDA Margin (%) | -7.8% | -18.7% | -15.4% | -0.4% | 12.2% |
| Profit Before Tax (PBT) | -₹342 | -₹448 | -₹148 | ₹22 | ₹340 |
| Net Profit / (Loss) (PAT) | -₹289 | -₹441 | -₹137 | ₹34 | ₹322 |
| Closing Order Backlog | ₹3,890 | ₹3,120 | ₹2,706 | ₹1,825 | ₹1,628 |
| Core Services Order Mix (%) | ~18% | ~24% | ~35% | ~52% | >65% |
(Financial data compiled from regulatory filings on BSE and NSE. FY26 net figures include operational recoveries and one-time settlement gains from BHEL and Jaypee).
                     REVENUE VS. EBITDA MARGIN TRAJECTORY

   Revenue (₹ Cr)                                       EBITDA Margin (%)
     3,000 ┬  ₹2,620                                        ┌─ +15%
           │    │                                           │
     2,000 ┤    └──► ₹1,796                                 ├─ +10%
           │           │                                    │
     1,000 ┤           └──► ₹1,039 ──► ₹1,047 ──► ₹1,269    ├─  0%  ── (FY25 Breakeven)
           │                                                │
         0 ┴─────────────────────────────────────────────── ┴─ -20%
               FY22       FY23       FY24      FY25     FY26
               [-7.8%]   [-18.7%]   [-15.4%]  [-0.4%]  [+12.2%]  <-- EBITDA Margin
Financial Trends to Note
- Strategic Revenue Contraction: Top-line turnover fell sharply between FY22 and FY24 as management systematically exited fixed-price EPC contracts. Once lower-quality orders were cleared, higher-margin services drove revenue back up to ₹1,269 Cr in FY26 (+21.2% YoY).
- Operating Margin Recovery: EBITDA margins improved from -18.7% in FY23 to +12.2% in FY26. Management maintains an 11% normalized EBITDA margin as an operational floor, with higher realizations during active outage quarters.
- Liquidity and Equity Expansion: Total net worth expanded from ₹57 Cr in March 2024 to ₹483 Cr by March 2026. Available liquidity expanded to ₹880 Cr, alongside a reduction of over ₹1,364 Cr in contingent bank guarantee liabilities.
6. Balance Sheet Evolution in the GE Power India Turnaround
Another critical pillar of the GE Power India turnaround is the resolution of legacy claims and balance sheet overhangs.
During previous years, substantial capital remained trapped in commercial disputes. Management tackled this directly:
- BHEL Arbitration Resolution: GEPIL reached a comprehensive settlement with Bharat Heavy Electricals Ltd (BHEL), yielding a milestone net cash recovery of ₹343 Cr and clearing ₹423 Cr in bank guarantee encumbrances.
- Private Developer Settlements: The company closed bilateral settlements with private power utilities (including the Jaypee Group), removing prolonged legal liabilities.
- Credit Rating Upgrades: Bolstered by positive operational cash flows and reduced contingent risk, rating agencies upgraded the company’s long-term credit facility to BBB+ (Stable).
7. Strategic Demerger: Transfer of Durgapur Unit to JSW Energy
A cornerstone of the GE Power India turnaround strategy has been the demerger of the Durgapur manufacturing unit to JSW Energy.
                     DURGAPUR DEMERGER STRUCTURE

        GE POWER INDIA LTD (GEPIL)            JSW ENERGY LTD
         (Retaining Services, Tech,           (Acquiring Heavy Fabrication,
          Turbine Overhauls & O&M)            Boiler Components & Mills)
                     │                                     │
                     └───────────────┬─────────────────────┘
                                     │
                           VALUE DISTRIBUTION RATIO:
                       10 Equity Shares of JSW Energy
                                     for
                          Every 139 Shares of GEPIL
Strategic Implications of the Scheme
- Asset Demerger Terms: The arrangement transfers GEPIL’s Durgapur manufacturing undertaking—specializing in boiler components, pressure vessels, and pulverizer coal mills—to JSW Energy as a going concern.
- Share Entitlement Ratio: Under the court-approved scheme, qualifying GEPIL shareholders receive 10 fully paid equity shares of JSW Energy (FV ₹10) for every 139 equity shares held in GEPIL.
- Leaner Capital Base: Heavy fabrication units entail significant fixed overheads and maintenance costs during industrial down-cycles. Carving out the manufacturing plant leaves GEPIL with an asset-light, services-focused profile with reduced capital intensity.
Stay informed on thematic capital goods plays with our curated power sector stocks coverage.
8. Peer Matrix: Evaluating Capital Goods Competitors
To assess valuation and capital efficiency, we compare GEPIL with its listed peer group: Bharat Heavy Electricals Ltd (BHEL), Thermax Ltd, Triveni Turbine, and Siemens Energy India.
Comparative Operating Matrix
| Company Name | Market Cap Segment | Core Revenue Driver | Working Capital Cycle | Normalized EBITDA Margin | Business Model Character |
| GE Power India (GEPIL) | Small-to-Mid Cap | Turbines, Boilers, Services, FGD | 30 to 60 Days (Asset-Light) | 11% to 13% (Target Floor) | Proprietary IP & Outage Services |
| BHEL | Large Cap | Mega-EPC, Defense, Railways, Thermal | High (Significant retention assets) | 4% to 7% (Historically cyclical) | Heavy PSU Manufacturing & Turnkey Civil |
| Thermax Ltd | Large Cap | Green Energy, Boilers, Water Treatment | Moderate | 8% to 10% | Industrial Engineering Solutions |
| Triveni Turbine | Mid Cap | Sub-100 MW Industrial Steam Turbines | Low (Strong cash flow conversion) | 19% to 22% | High-Margin Manufacturing & Exports |
| Siemens Energy India | Large Cap | Gas, Grid Infrastructure, Decarbonization | Moderate | 12% to 15% | High-Tech Energy Infrastructure |
                       PEER MARGIN VS. WORKING CAPITAL PROFILE

     EBITDA Margin (%)
         25% ┬                                     [Triveni Turbine]
             │
         20% ┤
             │                       [Siemens Energy]
         15% ┤       [GE Power India]
             │         (Turnaround)
         10% ┤                               [Thermax]
             │
          5% ┤                                             [BHEL]
             │
          0% ┴───────────────────────────────────────────────────────────►
             Low                                                High
                              Working Capital Days
Strategic Peer Takeaways
- BHEL captures substantial order volumes from new greenfield 800 MW thermal units commissioned by NTPC, but its heavy balance-sheet exposure results in single-digit EBITDA margins.
- Triveni Turbine operates effectively in smaller industrial steam turbines (<100 MW), but does not serve large-scale utility boilers and 500–800 MW supercritical steam turbines.
- GE Power India holds a distinct position: it retains OEM rights across a major portion of India’s utility-scale thermal fleet, allowing it to pursue high-margin aftermarket services without taking on turnkey construction liabilities.
9. Corporate Governance: The GE Vernova Architecture
An essential dimension of the investment thesis is GEPIL’s parentage and promoter backing.
Following the global corporate separation of General Electric into three listed entities—GE Aerospace, GE HealthCare, and GE Vernova (NYSE: GEV)—GE Power India’s majority promoter holding (68.58%) sits within GE Vernova’s energy business via GE Steam Power International BV.
                             GE VERNOVA CORPORATE TREE

                                 GE VERNOVA (Global)
                                         │
                             ┌───────────┴───────────┐
                             │                       │
                     GE Vernova T&D          GE Power India Ltd
                     (Power Grid /           (Steam Power, Boilers,
                      Transmission)           Turbines, Services)
                             │                       │
                      ~68.6% Promoter         ~68.6% Promoter
                          Holding                 Holding
Governance Checkpoints
- Strategic Focus: GE Vernova is prioritizing electrification, emissions reduction, and high-margin services globally. GEPIL’s restructuring in India mirrors this direction.
- Audit Oversight: In line with corporate governance standards, GEPIL’s board re-appointed Deloitte Haskins & Sells as Statutory Auditors and engaged Ernst & Young LLP for internal audit oversight.
- Institutional Ownership: Institutional participation has historically lagged compared to sister entity GE Vernova T&D India. Greater clarity on long-term promoter plans could help expand market liquidity.
Corporate updates can be monitored through the Securities and Exchange Board of India (SEBI) and the BSE Corporate Announcements Page.
10. Future Scenarios: Modeling the GE Power India Turnaround (FY27–FY29)
To evaluate potential risk-reward outcomes, we project three operating scenarios for the business over the next three fiscal years:
               PROJECTED EBITDA MARGIN TRAJECTORY (FY27 – FY29)

   EBITDA Margin (%)
     18% ┬
         │                                               Bull Case: ~15.5%
     14% ┤                                       ┌────────────────────────
         │                       Base Case: ~12% │
     10% ┤               ────────────────────────┼────────────────────────
         │
      6% ┤  Bear Case: ~7%
         │  ─────────────────────────────────────┴────────────────────────
      0% ┴────────────────────────────────────────────────────────────────
            FY26 (Turnaround Baseline)                 FY28–FY29 Target
Scenario Breakdown
1. Bull Case: Accelerated Services and Non-OEM Scale (Probability: 30%)
- Catalysts: Core services expand to over 75% of total sales. NTPC and state utilities accelerate 20-to-30-year life extension orders. Non-OEM turbine retrofits continue to see strong demand across private generators.
- Projections: Revenues expand to ₹1,650–₹1,850 Cr; normalized EBITDA margins reach 14.0%–16.0%; free cash flow conversion tops 80%; ROCE exceeds 25%.
2. Base Case: Steady Services with Selective FGD (Probability: 55%)
- Catalysts: Core services grow at a consistent 10%–12% annual rate; legacy FGD contracts wrap up without liquidated damages; Durgapur separation concludes cleanly.
- Projections: Revenues stabilize around ₹1,350–₹1,500 Cr; EBITDA margins hold within the management-guided band of 11.0%–12.5%; working capital remains stable at 45–60 days.
3. Bear Case: Outage Deferrals and Capex Delays (Probability: 15%)
- Catalysts: State generation utilities postpone planned outages during periods of peak power deficits; lingering legacy contracts incur minor warranty costs.
- Projections: Revenues decline to ₹1,000–₹1,150 Cr; EBITDA margins contract to 6.0%–8.0%; cash conversion slows due to extended payment verification cycles.
11. Monitoring Checklist: Key Risks and Variables
Turnaround strategies require consistent monitoring of quarterly operational metrics:
                            QUARTERLY MONITORING CHECKLIST

 ┌───────────────────────────┬───────────────────────────┬───────────────────────────┐
 │   ORDER INFLOW MIX        │    CASH CONVERSION        │     MARGIN STABILITY      │
 ├───────────────────────────┼───────────────────────────┼───────────────────────────┤
 │ Track % share of Core     │ Monitor Operating Cash    │ Verify whether normalized │
 │ Services vs. turnkey EPC  │ Flow vs. EBITDA. Cash conversion│ EBITDA stays consistently │
 │ in new quarterly bookings.│ should track above 75%.   │ at or above the 11% floor.│
 └───────────────────────────┴───────────────────────────┴───────────────────────────┘
- Core Services Share: Confirm that recurring services and spares maintain a leading share of total quarterly bookings.
- Cash Flow vs. EBITDA: Ensure that reported operating profits convert reliably into actual cash flows rather than unbilled revenue.
- State Utility Receivables: Track debtor days from state electricity boards (GENCOs) to assess payment discipline.
- National Thermal PLF: Monitor monthly CEA reports. Thermal PLFs above 65% signal ongoing demand for fleet maintenance and modernization.
In summary, the GE Power India turnaround demonstrates how an industrial equipment manufacturer can unlock balance sheet value by shifting away from low-margin EPC contracting toward high-margin, cash-generative fleet services right as India’s power supercycle gains momentum.
Community Discussions & Live Market Coverage
Stay connected with fundamental research breakdowns, balance sheet analyses, and institutional market insights:
📲 Connect With Our Research Channels
- 🔹 Join our Telegram Channel: Multibagger Hunts
- 🔹 Join our WhatsApp Community: Click to Join WhatsApp Channel
- 🔹 Follow us on X (Twitter): @multibagger360
- 🔹 Connect on Facebook: Multibagger Research Page
Community Highlights:
- ✅ Free, research-driven educational content
- ✅ Real-time earnings updates and balance sheet teardowns
- ✅ Curated fundamental breakdowns for long-term investors
Disclaimers & Disclosures
- Disclaimer: This article is for educational purposes only and does not constitute financial or investment advice. Investors should conduct their own independent research and consult a registered financial advisor before making investment decisions.
- Disclaimer: Projections of financial metrics and business scenarios are based on historical performance, management disclosures, and publicly available sector reports. Actual results may vary depending on macroeconomic shifts, commodity cycles, regulatory developments, and corporate execution.
- ⚠️ Not SEBI Registered: We are not SEBI-registered advisors. This analysis is prepared purely to share fundamental research insights and promote financial literacy. No paid advisory or stock-tipping services are offered.