admin
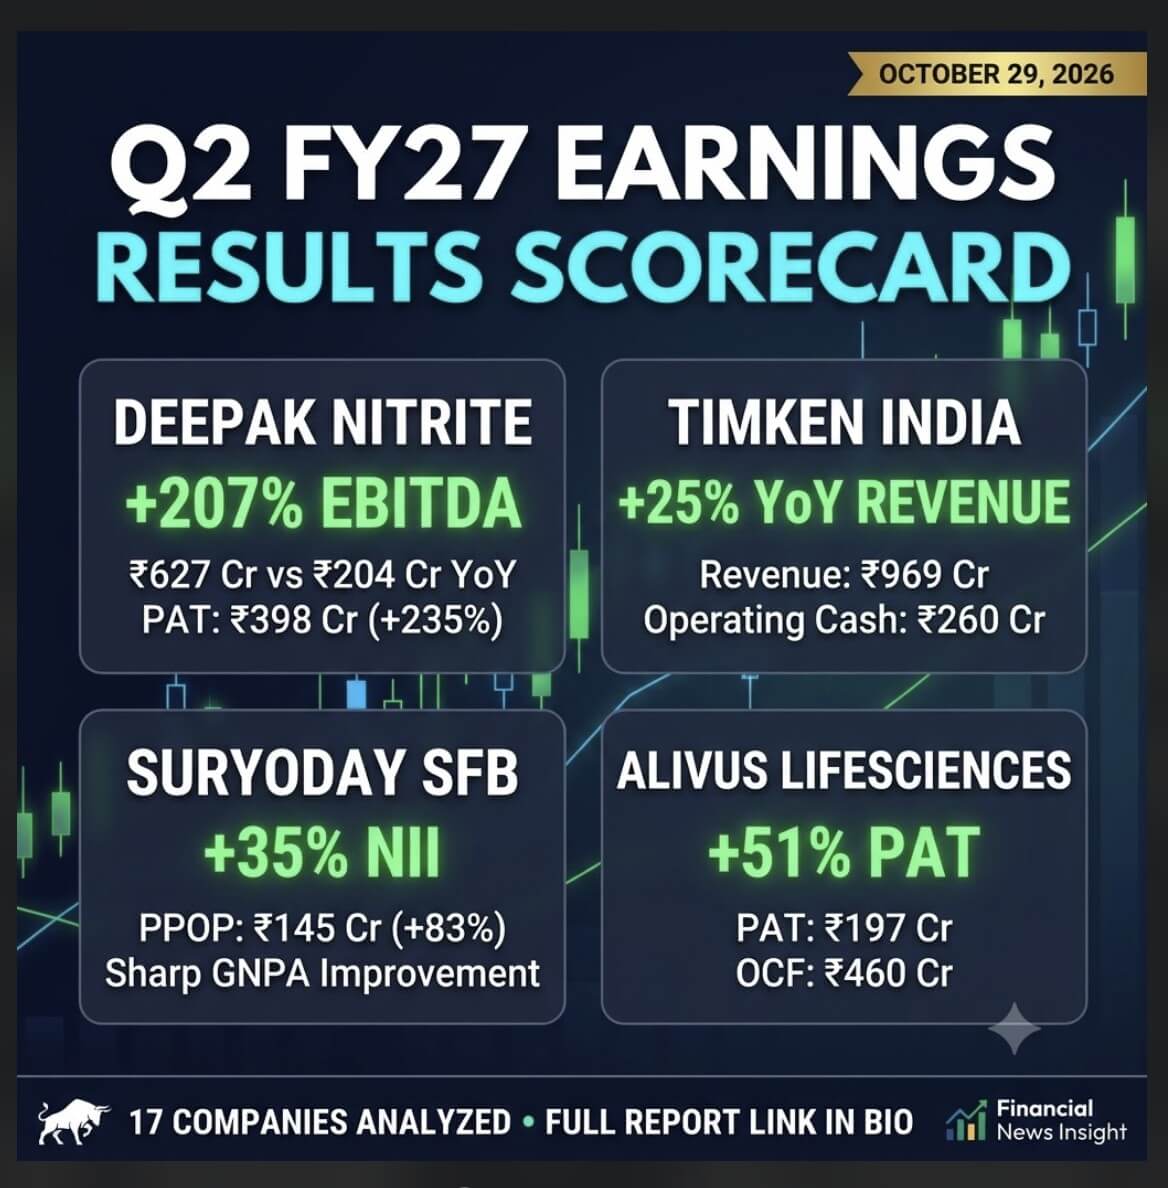
Corporate earnings for the second quarter of fiscal year 2027 (Q2 FY27) declared on October 29, 2026, underscore a distinct divergence in business fundamentals across India Inc. While domestic demand and post-monsoon manufacturing momentum supported mid-tier industrials and specialty players, bottom-line delivery remains bifurcated between companies with genuine cash realization and those experiencing working capital drag.
Financial reports from over 25 listed and leading corporate entities across consumer dairy, precision engineering, energy, auto components, and financial intermediaries highlight three key market dynamics:
- Operating Leverage Surges: High-capacity utilization driven by festive order books generated outsized profit expansion in select auto ancillaries and value-added consumer dairy.
- Turnaround Normalization: Multi-quarter loss-making operations across bulk formulations and resource extraction flipped back to profitability.
- The Quality-of-Earnings Wedge: Companies showing rapid top-line growth accompanied by negative Operating Cash Flows (OCF) signal elevated trade receivables and inventory lockups.
Fundamental investors cross-checking corporate announcements can reference the National Stock Exchange of India (NSE) Announcements and standard valuation frameworks through our Fundamental Equity Screening Guide.
1. High-Growth Leaders: Operating Leverage at Scale
Companies in this tier paired double-digit revenue expansion with robust operating margins and verified cash generation.
Milky Mist Dairy Food: Value-Added FMCG Outlier
Milky Mist posted its highest-ever quarterly earnings set, establishing a benchmark for product premiumization:
- Revenue: ₹1,089 crore versus ₹769 crore in Q2 FY26 (up 41.6% YoY) and ₹973 crore in Q1 FY27 (up 11.9% QoQ).
- Profit Before Tax (PBT): ₹90 crore versus ₹47 crore YoY (up 91.5%) and ₹73.5 crore QoQ.
- Profit After Tax (PAT): ₹78 crore versus ₹28 crore YoY (up 178.6%) and ₹65 crore QoQ.
- Operating Cash Flow (OCF): ₹229 crore versus ₹124 crore YoY.
Fundamental Assessment: Milky Mist’s structural shift away from commodity pouch milk toward high-margin value-added categories (paneer, cheese, butter, and Greek yogurt) protected its gross margin profile against regional milk procurement price hikes. Most importantly, OCF of ₹229 crore covered 293% of reported PAT, confirming high-quality cash realization without excessive channel credit.
Omax Autos: The Operating Leverage Rebound
- Revenue: ₹164 crore versus ₹89 crore YoY (up 84.3%) and ₹122 crore QoQ (up 34.4%).
- PBT: ₹16.7 crore versus ₹4.0 crore YoY (up 317.5%) and ₹13.7 crore QoQ.
- PAT: ₹11.6 crore versus ₹0.33 crore YoY and ₹10.6 crore QoQ.
- OCF: ₹29 crore versus ₹19 crore YoY.
Fundamental Assessment: As commercial vehicle and two-wheeler assemblies accelerated production runs ahead of the festive quarter, Omax Autos crossed its fixed-cost absorption threshold. A modest 34.4% sequential top-line increase enabled PAT to expand from ₹0.33 crore to ₹11.6 crore YoY, supported by ₹29 crore in cash flow from operations.
Ram Ratna Wires: Capital Expenditure Direct Beneficiary
- Revenue: ₹1,961 crore versus ₹1,163 crore YoY (up 68.6%) and ₹1,853 crore QoQ.
- PBT: ₹53 crore versus ₹32 crore YoY (up 65.6%) and ₹48 crore QoQ.
- PAT: ₹36 crore versus ₹22 crore YoY (up 63.6%) and ₹35 crore QoQ.
- OCF: ₹81 crore versus -₹183 crore in the previous comparative cycle.
Fundamental Assessment: As industrial electrification, EV motors, and transformer capacity expansion gathered pace, winding wire shipments grew significantly. Ram Ratna demonstrated margin control via raw-material passthrough pricing. The defining operational improvement was the swing in OCF to +₹81 crore from a working-capital-draining -₹183 crore.
2. Balance Sheet Turnarounds: Profitability Restored
Assets that previously weighed on corporate return ratios delivered positive operational recoveries during Q2 FY27.
Vedanta Oil and Gas (VOGL): Realization Stabilization
- Revenue: ₹2,486 crore versus ₹2,330 crore YoY and ₹2,507 crore QoQ.
- PBT: ₹775 crore versus ₹113 crore YoY and ₹114 crore QoQ.
- PAT: ₹746 crore (reversing net losses from the previous two quarters).
- OCF: ₹2,230 crore versus ₹1,517 crore YoY.
Fundamental Assessment: Despite a flat revenue trajectory (down 0.8% QoQ), PBT surged to ₹775 crore. The performance was driven by reduced operational lifting expenses, stabilized crude realizations, and an absence of one-time impairment charges. Generating ₹2,230 crore in OCF provides essential liquidity for upstream capital commitments.
Bharat Parenterals: Injectable & Formulation Recovery
- Revenue: ₹136 crore versus ₹65 crore YoY (up 109.2%) and ₹94 crore QoQ.
- PBT: ₹14 crore (recovering from net operational losses in the preceding two quarters).
- PAT: ₹12 crore.
- OCF: ₹83 crore versus ₹38 crore YoY.
Fundamental Assessment: Small-cap contract manufacturers often suffer from uneven order realization. Bharat Parenterals completed its recovery phase with top-line doubling YoY and generating ₹83 crore in cash flow, confirming that semi-regulated export markets have resumed normal shipment clearance.
Horizon Industrial Parks: Warehousing Cash Engine
- Revenue: ₹215 crore versus ₹166 crore YoY (up 29.5%) and ₹200 crore QoQ.
- EBITDA: ₹173 crore versus ₹130 crore YoY (33.1% growth, 80.5% margin).
- Other Income: ₹37 crore versus ₹10 crore YoY.
- PBT & PAT: PBT reached ₹10 crore (versus -₹73 crore YoY); PAT reached ₹14 crore (versus -₹74 crore YoY).
- OCF: ₹291 crore versus ₹199 crore YoY.
Fundamental Assessment: While Horizon’s 80.5% EBITDA margin illustrates the strong unit economics of Grade-A logistics assets, PBT of ₹10 crore was heavily bolstered by other income (₹37 crore). The core operational turnaround is advancing, with ₹291 crore in OCF providing strong debt-service coverage.
3. Specialized Compounders: Steady Margin Protectors
Consistent compounders are defined by structural market niches, steady order flows, and disciplined balance sheet practices.
Shaily Engineering Plastics: Medical Device Mix Shift
- Revenue: ₹320 crore versus ₹257 crore YoY (up 24.5%) and ₹281 crore QoQ.
- PBT: ₹85 crore versus ₹66 crore YoY and ₹66 crore QoQ (up 28.8% sequentially).
- PAT: ₹61 crore versus ₹51 crore YoY and ₹48 crore QoQ.
- OCF: ₹110 crore versus ₹98 crore YoY.
Fundamental Assessment: Shaily Engineering continues to benefit from its strategic shift into high-precision medical applicators, pen injectors, and specialized engineering assemblies. These complex tooling categories shield the company from polymer raw-material fluctuations and deliver healthy cash conversion.
Bliss GVS Pharma: Frontier Market Resilience
- Revenue: ₹313 crore versus ₹244 crore YoY (up 28.3%) and ₹285 crore QoQ.
- PBT: ₹75 crore versus ₹41 crore YoY (up 82.9%) and flat QoQ.
- PAT: ₹53 crore versus ₹29 crore YoY and ₹52 crore QoQ.
- OCF: ₹192 crore versus ₹137 crore YoY.
Fundamental Assessment: Bliss GVS preserved its market leadership in specialized suppository formulations across target emerging markets. While sequential profit before tax remained flat due to elevated ocean freight rates, the company generated ₹192 crore in cash flow from operations, supporting balance sheet stability.
Nintec Systems: Steady Mid-Tier IT Delivery
- Revenue: ₹48 crore versus ₹42 crore YoY and ₹46 crore QoQ.
- PBT: ₹14 crore versus ₹10 crore YoY and ₹12 crore QoQ.
- PAT: ₹10.5 crore versus ₹7.8 crore YoY and ₹9.2 crore QoQ.
- OCF: ₹25 crore versus ₹14 crore YoY.
Fundamental Assessment: In an enterprise tech spending climate marked by delayed approvals, Nintec produced predictable double-digit gains. An OCF-to-PAT ratio exceeding 200% confirms strong billing discipline and predictable offshore project delivery.
4. Financial Services & IT Services
Capital market intermediaries and digital process management providers encountered varying volume environments.
Motilal Oswal Financial Services: Market Cycle Beta
- Revenue: ₹3,041 crore versus ₹1,849 crore YoY (up 64.5%), but down from ₹3,425 crore in Q1 FY27 (-11.2%).
- PBT: ₹1,332 crore versus ₹504 crore YoY, down from ₹1,534 crore in Q1 FY27 (-13.2%).
- PAT: ₹1,081 crore versus ₹363 crore YoY, down from ₹1,272 crore in Q1 FY27 (-15.0%).
Fundamental Assessment: Brokerage, wealth management, and proprietary treasury books reflect market cyclicality. While YoY figures benefited from strong retail equity participation, the sequential pullback reflects market cooling and treasury mark-to-market adjustments. Investors must assess capital market institutions across full multi-year cycle earnings.
Firstsource Solutions (FSL): BPO & Platform Stability
- Revenue: ₹2,824 crore versus ₹2,311 crore YoY (up 22.2%) and ₹2,730 crore QoQ.
- PBT: ₹299 crore versus ₹222 crore YoY (up 34.7%) and ₹291 crore QoQ.
- PAT: ₹232 crore versus ₹179 crore YoY and ₹166 crore QoQ.
- OCF: ₹496 crore versus ₹593 crore YoY.
Fundamental Assessment: Firstsource delivered balanced top-line growth across healthcare and banking verticals. Sequential net profit climbed from ₹166 crore to ₹232 crore, maintaining steady operational performance.
IndoStar Capital Finance: Cautious Credit Underwriting
- Net Interest Income (NII): Up 8% YoY.
- PBT: ₹13.0 crore versus ₹10.5 crore YoY and ₹11.4 crore QoQ.
- Asset Quality: Gross NPA at 4.46%; Net NPA at 2.44%.
Fundamental Assessment: IndoStar is prioritizing underwriting discipline over aggressive loan-book growth. Although earnings metrics are stabilizing, maintaining adequate provisioning against a 2.44% Net NPA remains essential for commercial vehicle portfolio health.
5. Working Capital Warning: Profit vs. Cash Divergences
Elevated accounting profit can mask underlying stress if receivables or inventory expand disproportionately. Investors should closely track companies exhibiting negative operating cash flows.
KRN Heat Exchangers: The Working Capital Stasis
- Revenue: ₹319 crore versus ₹152 crore YoY (up 109.9%) and ₹252 crore QoQ.
- PAT: ₹36 crore versus ₹18 crore YoY (flat QoQ).
- Operating Cash Flow (OCF): -₹133 crore (driven by a sharp increase in trade receivables).
Fundamental Assessment: Although KRN doubled sales YoY, cash flow from operations plunged to -₹133 crore. Offering extended credit terms allows top-line acceleration, but reliance on short-term debt to fund working capital increases balance sheet vulnerability.
Anlon Healthcare: Record Sales vs. Persistent Negative Cash
- Revenue: ₹105 crore versus ₹52 crore YoY and ₹88 crore QoQ.
- PAT: ₹17 crore versus ₹9 crore YoY and ₹8 crore QoQ.
- Operating Cash Flow (OCF): -₹8 crore versus -₹78 crore YoY.
Fundamental Assessment: Anlon reported record revenue and doubled its net profit sequentially, but operational cash flow remained in negative territory at -₹8 crore. While improving from -₹78 crore YoY, receivables collection requires verification over upcoming quarters.
Borosil Ltd: Inventory Absorption Ahead of Demand
- Revenue: ₹369 crore versus ₹344 crore YoY and ₹258 crore QoQ.
- PAT: ₹32 crore versus ₹23 crore YoY and ₹13 crore QoQ.
- Operating Cash Flow (OCF): -₹3 crore versus +₹50 crore YoY.
Fundamental Assessment: Borosil exhibited notable operational acceleration, with PAT expanding from ₹13 crore to ₹32 crore QoQ. However, working capital turned cash flows to -₹3 crore due to pre-festive seasonal inventory buildup.
Micro-Cap Divergences: RNIT AI & Praruh Technologies
- RNIT AI Solutions: Revenue grew to ₹16 crore (up 100% QoQ) and PBT reached ₹5.6 crore. However, OCF stood at -₹7 crore, reflecting milestone billing lags typical of early-stage enterprise software engagements.
- Praruh Technologies: Revenue surged to ₹84 crore from ₹18 crore YoY, with PBT at ₹11 crore, but OCF registered at -₹4 crore due to front-loaded project deployment costs.
- Tarachand Infra: Revenue expanded to ₹83 crore from ₹66 crore YoY, with EBITDA at ₹28 crore and PAT reaching ₹9 crore, benefiting from domestic infrastructure equipment deployment.
6. Heavyweights, Energy, and Infrastructure Updates
Market infrastructure institutions and index heavyweights posted steady, lower-beta operational prints on October 29, 2026.
Coal India: Normalization After Record Highs
- PBT: ₹8,728 crore versus ₹5,991 crore YoY, but down sequentially from ₹11,719 crore in Q1 FY27.
- Fundamental Assessment: Higher coal dispatch volumes to power utilities supported YoY performance, but softening e-auction realization premiums drove sequential contraction.
Power & Utilities: Vedanta Power
- Revenue: ₹2,820 crore versus ₹2,097 crore YoY and ₹2,595 crore QoQ.
- PBT: ₹102 crore (recovering from net losses over the preceding two quarters).
- Fundamental Assessment: Improved plant load factors (PLF) and lower imported fuel blending costs enabled the power segment to return to operational profitability.
Market Infrastructure & Real Estate (CAMS, IEX, Brigade, IndraMedCo, RBA, ICRA)
- CAMS: Revenue rose 4.5% and PBT expanded 9%, compounding steadily alongside mutual fund equity AUM additions.
- Indian Energy Exchange (IEX): Generated 7% to 8% top- and bottom-line growth, backed by high merchant power clearing volumes.
- Brigade Enterprises: Revenue stood at ₹1,196 crore (versus ₹1,383 crore YoY), while PBT expanded to ₹288 crore from ₹196 crore YoY. This reflects real estate project completion cycles where revenue recognition aligns with unit handovers.
- Indraprastha Medical Corporation (IndraMedCo): Revenue reached ₹412 crore versus ₹381 crore YoY, with PBT steady at ₹72 crore, supported by resilient hospital bed occupancy.
- ICRA: Delivered revenue of ₹178 crore and PBT of ₹72 crore (flat QoQ), matching corporate debt syndication activity.
- Restaurant Brands Asia (RBA): Consolidated net losses continued to narrow as operating efficiencies took hold across its Burger King retail store network.
7. Master Financial Scorecard: Q2 FY27 (Declared 29th Oct 2026)
The table below summarizes performance metrics, operational trends, and earnings quality assessments across covered companies.
| Company Name | Sector | Revenue (₹ Cr) | PAT (₹ Cr) | OCF (₹ Cr) | Earnings Quality |
| Milky Mist | FMCG / Dairy | 1,089 | 78 | 229 | High: Record scale with high cash conversion |
| Vedanta Oil & Gas | Energy | 2,486 | 746 | 2,230 | Turnaround: Substantial cash generation |
| Ram Ratna Wires | Electrical Industrials | 1,961 | 36 | 81 | High: Strong volume and cash flow recovery |
| Shaily Engineering | Precision Plastics | 320 | 61 | 110 | High: Margin expansion with medical mix |
| Firstsource Solutions | IT / BPM | 2,824 | 232 | 496 | High: Consistent conversion and margins |
| Omax Autos | Auto Ancillaries | 164 | 11.6 | 29 | High Turnaround: Operating leverage inflection |
| Bliss GVS Pharma | Pharmaceuticals | 313 | 53 | 192 | Moderate-High: Steady margins in niche markets |
| Bharat Parenterals | Pharma Formulations | 136 | 12 | 83 | Turnaround: Profitable recovery across metrics |
| Horizon Ind. Parks | Logistics Infra | 215 | 14 | 291 | Moderate: High EBITDA; supported by other income |
| Motilal Oswal | Financial Services | 3,041 | 1,081 | N/A | Cyclical: Strong YoY; sequential cooling |
| Borosil Ltd | Consumer Ware | 369 | 32 | -3 | Watchlist: Sound demand; festive inventory tie-up |
| KRN Heat Exchangers | Industrial Cooling | 319 | 36 | -133 | High Risk: Rapid growth with negative OCF |
| Anlon Healthcare | Healthcare | 105 | 17 | -8 | Watchlist: Record accounting profits, negative OCF |
| Coal India | Mining & Coal | N/A | 8,728 (PBT) | N/A | Moderate: Steady dividend; lower e-auction rates |
| Vedanta Power | Utilities | 2,820 | 102 (PBT) | N/A | Turnaround: Rebounded from prior quarterly losses |
| Tarachand Infra | Infrastructure Support | 83 | 9 | N/A | Moderate: Stable margins on equipment leasing |
8. Portfolio Allocation Takeaways
For retail and institutional equity investors navigating post-earnings decisions on October 29, 2026, three disciplined portfolio strategies emerge:
- Prioritize Cash Flow Yield Over P/E Ratios: Accounting profit can be influenced by revenue recognition policies and credit terms. High OCF-to-PAT generators like Milky Mist and Shaily Engineering provide higher safety margins than high-multiple stocks facing extended cash conversion cycles like KRN Heat Exchangers.
- Capitalize on Structural Turnarounds: When a company transitions out of consecutive loss-making quarters—as seen with Omax Autos and Bharat Parenterals—operating leverage can fuel EPS growth that outpaces top-line revenue gains.
- Differentiate Secular Growth from Cyclical Highs: Brokerage and capital market beneficiaries such as Motilal Oswal require valuation adjustments that factor in market cycle peaks rather than extrapolating peak quarter earnings indefinitely.
Disclaimer: This article is for educational purposes only and not financial advice. Investors should do their own due diligence before investing.
Disclaimer: The projections of potential returns are based on current market conditions and company performance. Actual results may vary due to various factors, including market dynamics, economic conditions, and changes in the competitive landscape. Investors should conduct their own research and consult with financial advisors before making investment decisions.
Multibagger Stocks breakout stocks
⚠️ Not SEBI Registered—just here to share insights | 🚫 No paid services—everything shared is entirely free! 🧠 Always Learning and excited to grow together in this journey of market exploration.
📲 Join Our Investor Communities
🔹 Join our Telegram Channel: Multibagger Hunts
🔹 Join our WhatsApp Channel: Click to Join
✅ Free access
✅ Instant alerts
✅ Curated research for serious investors
Invest in Stocks
TwitterXWhatsAppThreadsTelegramFacebookLinkedInGmailEmailShare