admin
Deccan Gold Mines Q2 FY27 Analysis: 5.5x Profit Surge, Con-Call Insights & The Dec 1 Ganajur Trigger
Deccan Gold Q2 FY27 results mark a major turning point for India’s only listed gold mining company (BSE: 512068 | NSE: DECNGOLD). For over two decades, investors viewed the firm mainly as an exploration play awaiting mining approvals. However, management’s latest numbers and November 20, 2026 earnings call prove that the business now generates real mining profits.
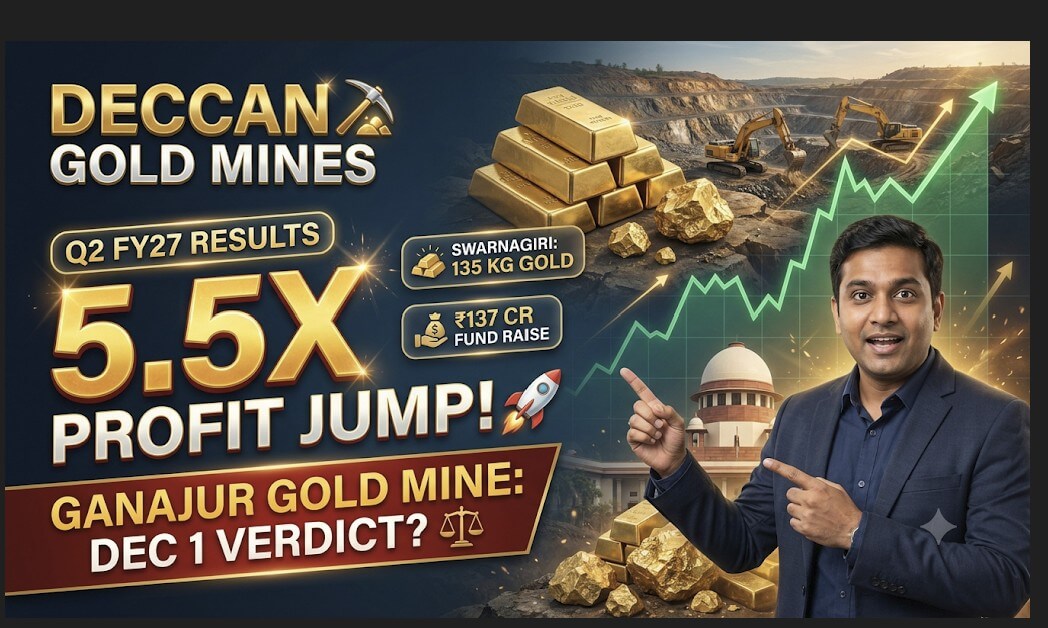
Specifically, standalone net profit jumped nearly 5.5 times quarter-on-quarter (QoQ) to ₹6.51 crore during July–September 2026. Higher gold output at the Swarnagiri project in Andhra Pradesh drove this strong turnaround. Meanwhile, the company shipped its first gold doré bar in Kyrgyzstan and won BSE approval for a ₹137 crore+ fundraise.
Above all, investors are watching a major legal trigger at the Supreme Court of India. For the first time, management dedicated a full presentation slide to the Ganajur Gold Mine case ahead of the December 1, 2026 hearing. Below, we examine the financial numbers, earnings call revelations, and key risks for investors.
(Insert your thumbnail image here with Alt Text: Deccan Gold Q2 FY27 profit surge and Ganajur case)
Deccan Gold Q2 FY27 Revenue Analysis: Standalone vs. Consolidated
At first glance, Deccan Gold Q2 FY27 revenue numbers can puzzle retail investors. Standalone total income surged 50.7% QoQ to ₹17.24 crore. In contrast, consolidated total income stood at just ₹2.44 crore. During the earnings call, the Chief Financial Officer (CFO) explained the exact accounting rules behind this gap.
3 Reasons Why Standalone Income Exceeds Consolidated Income
- Inter-Company Loan Interest: Deccan Gold Mines Ltd lent roughly ₹276 crore to its Kyrgyzstan subsidiary at 15% annual interest. Standalone books record this interest as revenue, whereas group consolidation removes inter-company interest completely.
- Technical Service Fees: The parent firm bills geological and engineering services to Avelum Partners in Kyrgyzstan at a modest margin. Similarly, accounting rules remove these internal service fees during group consolidation.
- Associate Profit Accounting: Deccan Gold holds a 26% stake in the producing Swarnagiri Gold Project as an associate entity. Therefore, Swarnagiri’s bullion sales do not enter Deccan Gold’s consolidated top line. Instead, Deccan Gold’s 26% share of net profit appears directly below the operating line.
Q2 FY27 & H1 FY27 Financial Performance Table
The table below compares standalone and consolidated results across Q1 FY27, Q2 FY27, and H1 FY27 from official BSE India filings:
| Financial Metric (₹ Crore) | Q1 FY27 (Apr–Jun ’26) | Q2 FY27 (Jul–Sep ’26) | QoQ Change (%) | H1 FY27 Total |
| Standalone Total Income | ₹11.44 Cr | ₹17.24 Cr | +50.70% | ₹28.68 Cr |
| Standalone Net Profit (PAT) | ₹1.18 Cr | ₹6.51 Cr | +451.69% (~5.5x) | ₹7.69 Cr |
| Standalone Net Profit Margin | 10.31% | 37.76% | +2,745 bps | 26.81% |
| Consolidated Total Income | ₹0.60 Cr | ₹2.44 Cr | +306.67% (~4.0x) | ₹3.04 Cr |
| Consolidated Net Profit / (Loss) | (₹8.73 Cr) | (₹0.55 Cr) | Loss Cut by 93.7% | (₹9.28 Cr) |
| Share of Associate Profit (Net) | ₹6.64 Cr | ₹14.20 Cr | +113.86% | ₹20.84 Cr |
Furthermore, standalone revenue grew 463.4% year-on-year (YoY) from ₹3.06 crore in Q2 FY26. The company swung from a net loss of ₹16.60 crore a year ago to a healthy profit today. Readers tracking similar turnaround stories can check our quarterly earnings breakdowns for more emerging stocks.
Profit Trends & Margin Expansion in Deccan Gold Q2 FY27
Historically, Deccan Gold posted weak return ratios because its mines were still under construction. For instance, FY26 Return on Equity (ROE) stood at -21.68%, while Return on Capital Employed (ROCE) stood at -12.62%. However, Deccan Gold Q2 FY27 numbers show strong operating leverage as gold output rises.
Key Margin & Cost Revelations from the Earnings Call
- Low Indian Production Cost: Managing Director Dr. Hanuma Prasad Modali shared exact unit costs on the call. Swarnagiri produces gold at roughly ₹4,000 per gram, whereas domestic bullion sells for ₹13,000 to ₹14,000 per gram.
- 70% Associate EBITDA Margins: Consequently, Swarnagiri earns an associate EBITDA margin of about 70% and a net profit margin near 50%. Even if gold prices dip moderately, management expects associate EBITDA margins to stay strong at 65% to 67%.
- 93.7% Drop in Consolidated Loss: On a consolidated basis, net loss shrank from ₹8.73 crore in Q1 FY27 to just ₹0.55 crore in Q2 FY27. Thus, Swarnagiri’s ₹13.91 crore profit share now nearly covers exploration costs across four foreign countries.
- Clear Path to Group Profit: Moreover, Kyrgyzstan will soon begin regular bullion settlements. As a result, Deccan Gold can achieve positive consolidated net profit in the coming quarters.
Swarnagiri Gold Project: Output Ramp-Up, ₹134 Cr Inventory & IPO Outlook
Located in Andhra Pradesh, Swarnagiri (Jonnagiri) is India’s first private-sector commercial gold mine. Today, this asset acts as the primary profit driver behind Deccan Gold Q2 FY27 performance.
Operational Milestones & FY27 Volume Guidance
- 52% Output Jump: Gold output rose to 135 kg in Q2 FY27, up from 89 kg in Q1 FY27. Therefore, cumulative H1 FY27 output reached 224 kg. Currently, the plant produces 40 to 45 kg per month from open-pit ore grading 1.4 to 1.5 g/t.
- 90–95% Gold Recovery: In addition, metallurgical recovery stayed between 90% and 95%. This high recovery rate confirms that the processing plant works efficiently.
- Higher Full-Year Guidance: Earlier, baseline targets pointed to ~400 kg for FY27. Now, management expects full-year output to reach 450 to 500 kg. Following new regulatory approvals, output will scale to 1,000+ kg per year, with a long-term goal of 2 tonnes per year.
Understanding the ₹134 Crore Inventory Catalyst (~133 Kg Gold)
Notably, Swarnagiri produced far more gold than it sold during the first half of FY27:
| Swarnagiri Production vs. Sales | Q1 FY27 | Q2 FY27 | H1 FY27 Cumulative |
| Gold Produced (kg) | 89.0 kg | 135.0 kg | 224.0 kg |
| Refined Bullion Sold (kg) | 58.5 kg | 50.4 kg | 108.9 kg |
| Closing Inventory Volume | — | — | ~133.0 kg (Doré + Bullion + Circuit) |
| Balance Sheet Inventory Value | — | — | ₹134.0 Crore (At Production Cost) |
Management highlighted two important facts about this ₹134 crore inventory:
- Valued at Cost, Not Market Price: Accounting rules value this ₹134 crore stockpile at actual mining and processing cost. It includes Run-of-Mine (ROM) ore, gold-in-circuit, doré bars, and refined bullion. Therefore, its real market selling value sits much higher than its book value.
- Q3 FY27 Revenue Boost: Specifically, management held back refined bullion in September 2026 to capture higher festive prices. Dr. Modali confirmed strong gold sales during October and November 2026. Accordingly, those sales will boost Q3 FY27 earnings directly.
Can Deccan Gold Increase Its 26% Stake or List Swarnagiri?
- No Equity Infusion Needed: Swarnagiri generated ₹79.13 crore in standalone H1 profit on ~₹160 crore revenue. Because internal cash flows fund all capex, the associate needs no fresh equity. Hence, Deccan Gold cannot raise its 26% stake through new share issues.
- Possible Future IPO: However, management noted that Swarnagiri’s board may explore a public listing after two or three more quarters. While Deccan Gold plans to hold its 26% stake, an IPO would unlock clear market value.
Ganajur Supreme Court Case: Legal Strategy & 2030 Commissioning Timeline
For long-term investors, the Ganajur Gold Project in Karnataka remains Deccan Gold’s richest domestic asset. Management dedicated an entire presentation slide to Ganajur ahead of the December 1, 2026 Supreme Court hearing.
Why Ganajur Is a High-Grade Prize
- Superior Ore Grade: Ganajur holds 9 to 10 tonnes (330,000 ounces) of proven open-pit gold at 3.8 g/t. That grade is nearly 2.7 times richer than Swarnagiri’s 1.4 g/t open-pit grade.
- 75–80% Margin Potential: Consequently, a 1,000 tonnes-per-day (tpd) plant can produce 3.2 to 3.3 kg of gold daily, or ~1 tonne yearly. Higher grades lower unit mining costs and support 75% to 80% operating margins.
Legal Strategy Ahead of December 1, 2026
- Strong Approval History: Unlike disputed auction cases, Ganajur moved smoothly from Reconnaissance Permit to Prospecting License and Mining Lease. Karnataka recommended the lease in 2010. Next, the Union Ministry of Mines granted prior approval in July 2015 and reaffirmed it in February 2017.
- 2026 Supreme Court Milestones: On June 9, 2026, the Supreme Court dismissed a PIL opposing the lease and protected pre-2015 vested rights. Later, in October 2026, the court agreed to hear impleadment pleas—including Deccan Exploration Services Private Limited (DESPL)—alongside the main appeals.
- December 1 Top-of-Board Hearing: At the November 17, 2026 hearing, judges decided to hear all connected cases holistically. At the Union of India’s request, the bench listed the case at the top of the board on December 1, 2026.
- Independent Senior Counsel: Some investors worried that co-petitioner Indsil holds a weaker legal claim. Therefore, Deccan Gold hired a top Supreme Court senior counsel to argue its independent ministerial approvals. Legal advisors expect clarity within four to five regular hearings. Investors can follow official updates on the Supreme Court of India portal.
Realistic Commissioning Timeline (Even on a Legal Win)
Management cautioned shareholders to stay realistic about construction timelines after any court victory:
- Lease Execution (~March 2027): First, a positive Supreme Court ruling will clear DESPL’s High Court writ petition for lease execution.
- Statutory Clearances (~6 Months): Second, the company needs final environmental and Indian Bureau of Mines (IBM) approvals.
- Plant Construction (18–24 Months): Finally, land acquisition and building the 1,000 tpd plant will take up to two years. Thus, realistic gold production would start around March 2030.
| Ganajur Scenario (Dec 1, 2026) | Potential Court Outcome | Valuation & Execution Impact |
| Strong Bull Case | Union of India backs prior 2015/2017 approvals; court affirms vested lease rights. | Unlocks a 1 tonne/year, 3.8 g/t mine; triggers major stock re-rating toward 2030 launch. |
| Base / Neutral Case | Hearings continue across 4–5 sessions into early 2027 before final verdict. | Near-term share consolidation; focus stays on Swarnagiri Q3 sales and Kyrgyzstan output. |
| Bear Case | Adverse ruling forces fresh competitive auction under amended mining laws. | Sharp sentiment hit to domestic exploration value, though Swarnagiri cash flows cushion downside. |
Altyn Tor (Kyrgyzstan): Ownership Math, Winter Test & Stake Hike Plan
Deccan Gold inaugurated the Altyn Tor Gold Project in Kyrgyzstan on September 12, 2026. Notably, this mine gives the company its first international gold cash flows.
Understanding the 49.8% Net Revenue Share & Stake Hike Plan
- Current Revenue Split: State-owned OJSC Kyrgyzaltyn receives 17% of gross revenue, while Avelum Partners retains 83%.
- Deccan Gold’s Net Share: Deccan Gold owns 60% of Avelum Partners alongside Hira Group (26%) and MedEdu (14%). Thus, Deccan Gold holds an effective ~49.8% net revenue interest.
- Plan to Buy More Equity: Importantly, management is negotiating to buy additional shares from co-partners in Avelum Partners. Raising its stake to 80% or 100% would consolidate nearly all of the 83% JV revenue into Deccan Gold.
Maiden Doré Refining & Winter Plant Test
- 1.2 Kg Maiden Doré Dispatch: In Kyrgyzstan, miners must refine doré bars at the state refinery and sell bullion to the National Bank. Management sent a 1.2 kg test bar for refining and expects final bank settlement within a week.
- Winter Stress Test: Meanwhile, engineers are processing 30,000 tonnes of ore (~30–35 kg gold) to test sub-zero winter operations. Management will finalize full-year FY27 output guidance after observing the next 15 to 20 days of winter performance.
- 35–40% PAT Margin Target: Over the next four years, Altyn Tor will process low-grade stockpiles at low operating cost. Management targets 300 kg output in FY28 at 35% to 40% net margins. Later, underground mining at 2.5–3.0 g/t will double output to 600–750 kg yearly.
Critical Minerals Engine, Offtake Financing & M&A Pipeline
While gold will generate roughly 60% of revenue over the next five years, critical minerals form Deccan Gold’s second major growth pillar. Global prices for tungsten (+622%) and tantalum (+100%) have soared, boosting the value of early-stage deposits.
Portfolio of Global Gold & Critical Mineral Projects
| Project & Location | Target Minerals | Current Status & Resource Data | Commercialization & Fiscal Edge |
| Bhalukona (Chhattisgarh) | Nickel, Copper & PGE | 15 drill holes (2,773m) done; 4+ Mt zone at 0.24% NiEq across 1.3 km. | Mining lease filing in H1 2027; pilot plant by 2028; 3,000 tpd plant by 2029. |
| Logrosán & Maria (Spain) | Tungsten, Tin & Antimony | 5,400m drilled; 2.3 Mt tungsten-tin zone; Maria hit >1,000 ppm antimony. | 0% tungsten royalty in Spain; 25% corporate tax; concentrates exportable to India. |
| Mozambique Concessions | Lithium & Tantalum | 150 sq km license across Inhaca & Mutala pegmatites; topsoil tantalum potential. | <3% lithium royalty; modular 200 tpd plant targeted for 2028 launch. |
| Kalevala Gold (Finland) | Gold | 2,700+ Ha Tier-1 European license; Kuikka & Pahkalampi grading ~3.5 g/t Au. | 2.5% royalty & 20% corporate tax; 1,000–1,500m drilling starting immediately. |
Non-Dilutive Offtake Deals & Government Grants
Instead of diluting shareholders to fund ₹400–₹600 crore processing plants, management is pursuing two smart funding routes:
- Customer Offtake Financing: First, industrial buyers have approached Deccan Gold for nickel, lithium, and tungsten offtake deals. Under these deals, customers pre-fund plant construction in exchange for guaranteed raw material supply.
- 20–30% Government Grants: Second, the Ministry of Mines, Government of India offers over ₹2,000 crore under the National Critical Mineral Mission. Management expects 20% to 30% capital subsidies for domestic nickel and battery-grade processing units.
3 New Acquisitions Under Due Diligence
In addition, management is conducting commercial due diligence on three promising assets:
- Finland Gold-Silver Deposit: A 45 sq km license holding 6 tonnes of gold and 9 tonnes of silver near Kalevala.
- Brownfield Gold Mine Near Altyn Tor: An existing deposit with 3.3 tonnes of gold (plus silver and copper) that can scale past 10 tonnes.
- Large-Flake Battery Graphite Project: A 10 km zone with 5 mm jumbo flakes and 94% flotation recovery for EV battery anodes.
For deeper coverage of domestic policy tailwinds—including the PIB MMDR Amendment Act 2026 capping state mineral levies—visit our small-cap stock research hub.
Capital Raise & Risks After Deccan Gold Q2 FY27
Following Deccan Gold Q2 FY27 results, the company received final BSE approval to raise ₹137 crore+ via CCDs, equity shares, and warrants. Management expects to close fund collection within days to launch drilling in Finland, Spain, and Mozambique. Furthermore, the team plans institutional analyst roadshows before December 15, 2026.
5 Key Investment Risks to Monitor
- Binary Court Risk on Ganajur: Any adverse ruling or prolonged delay on December 1, 2026 could trigger sharp short-term stock volatility.
- Kyrgyzstan Winter Weather: Sub-zero winter temperatures during Q3 FY27 could slow early doré output during Altyn Tor’s first winter test.
- Multi-Country Execution: Running exploration and mining across five nations simultaneously stretches management bandwidth and carries currency risks.
- Long Project Timelines: Commercial cash flows from Mozambique and Bhalukona pilot plants will not start until 2028, while Ganajur targets 2030.
- Gold Price Swings: Swarnagiri’s 70% EBITDA margin relies on strong bullion prices (~₹13,000–₹14,000/gm); a steep gold correction would trim margins.
Frequently Asked Questions (FAQ)
1. Why did standalone net profit jump 5.5x in Deccan Gold Q2 FY27? Standalone net profit rose from ₹1.18 crore in Q1 FY27 to ₹6.51 crore in Q2 FY27. Specifically, Swarnagiri gold output jumped 52% to 135 kg, doubling Deccan Gold’s associate profit share to ₹13.91 crore.
2. Why is standalone revenue higher than consolidated revenue? As explained on the earnings call, standalone revenue includes 15% interest on a ₹276 crore loan to Kyrgyzstan plus consultancy fees. Consolidation removes these inter-company transactions.
3. What happened to the ₹134 crore gold inventory from Q2 FY27? Management held ~133 kg of doré and bullion (valued at ₹134 crore at cost) at September-end for India’s festive season. Strong bullion sales took place in October–November 2026 and will appear in Q3 FY27 results.
4. When will Ganajur start producing gold if Deccan Gold wins in court? Even if the court clears the lease by March 2027, environmental permits, land acquisition, and plant construction take roughly three years. Therefore, realistic production targets March 2030.
5. What is Deccan Gold’s net revenue share in Kyrgyzstan? State-owned Kyrgyzaltyn takes 17% of revenue, while Avelum Partners takes 83%. Since Deccan Gold owns 60% of Avelum Partners, its net share equals ~49.8%, with talks underway to buy a larger stake.
Educational Disclaimer: This article is for educational and informational purposes only and does not constitute investment advice. Small-cap mining stocks carry high regulatory, geological, and market risks. Always verify financial data from officialDeccan Gold Mines filingsand BSE/NSE releases before investing.
Disclaimer: The projections of potential returns are based on current market conditions and company performance. Actual results may vary due to various factors, including market dynamics, economic conditions, and changes in the competitive landscape. Investors should conduct their own research and consult with financial advisors before making investment decisions.
Multibagger Stocks breakout stocks
⚠️ Not SEBI Registered—just here to share insights | 🚫 No paid services—everything shared is entirely free! 🧠 Always Learning and excited to grow together in this journey of market exploration.
📲 Join Our Investor Communities
🔹 Join our Telegram Channel: Multibagger Hunts
🔹 Join our WhatsApp Channel: Click to Join
✅ Free access
✅ Instant alerts
✅ Curated research for serious investors
Invest in Stocks
TwitterXWhatsAppThreadsTelegramFacebookLinkedInGmailEmailShare